

2026 Chevy Corvette Credit: GM
KEY TAKEAWAYS
- October new-vehicle total sales on track for a seasonally adjusted selling rate of 15.6M, the same as October 2025
- Retail sales will decrease 1.4% on a selling-day-adjusted basis, but rise 2.3% on a non-selling-day-adjusted basis
- Hybrid share of retail sales expected to reach 18.6%, up 4.0 percentage points
- Average monthly payments expected to rise 2.6% to an October record of $823, while interest rates are projected to rise 19 basis points to 6.81%, the highest October level since 2023
The Total Sales Forecast
October 24, 2026 - Total new-vehicle sales for October 2026, including retail and non-retail transactions, are projected to reach 1,327,100, a 0.2% increase year over year, according to a joint forecast from JD Power and GlobalData. Reporting the same numbers without adjusting for the number of selling days translates to an increase of 3.9% from October 2025. The seasonally adjusted annualized rate (SAAR) for total new-vehicle sales is expected to be 15.6 million units, flat from 2025.
The Retail Sales Forecast
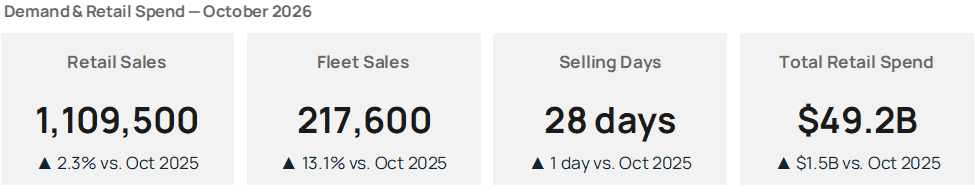
New-vehicle retail sales for October 2026 are projected to reach 1,109,500, a 1.4% decrease from October 2025. Reporting the same numbers without adjusting for the number of selling days translates to an increase of 2.3% from 2025. The SAAR for retail new-vehicle sales is expected to be 13.0 million units, down 0.2 million units from October 2025.
Thomas King, president of OEM solutions at JD Power:
“October results reflect the continued resilience of new-vehicle demand, with total sales on pace to rise 0.2% year over year, or 3.9% without adjusting for selling days. The year-over-year comparison to October 2025 is flattered by what happened a year ago, when the payback from September 2025’s EV tax-credit surge suppressed volumes. Retail sales are on pace to decline 1.4% on a selling-day-adjusted basis, however, they will be up 2.3% without adjusting for selling days.
“Retail consumer expenditure on new vehicles is projected to increase 3.2% to $49.2 billion, an increase of $1.5 billion from October 2025, helped by the additional selling day and transaction prices just slightly below last year’s level.
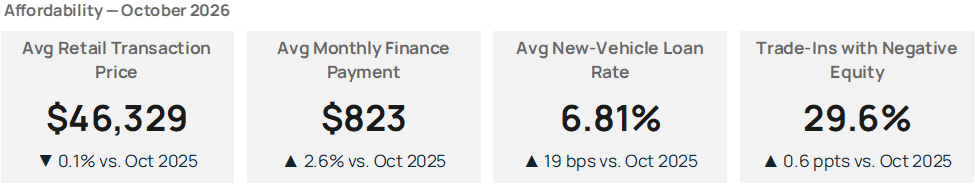
“Affordability remains a headwind. The average monthly payment is expected to rise 2.6% even as the average transaction price is forecast to dip 0.1%. Higher interest rates and lower trade-in equity are driving the gap, increasing both the amount financed and the cost of financing it.
“The average transaction price of a new vehicle is trending down slightly to $46,329, however average monthly finance payments are forecasted to climb to $823, the highest ever for the month of October.
“A key driver of the higher monthly payment, despite longer loan terms, is lower trade-in equity. Many buyers returning to showrooms today purchased when prices were at their peak several years ago, when inventory was scarce. This is manifesting itself as more buyers carrying negative equity on their trade-ins. In October, 29.6% of trade-ins are projected to have negative equity, up 0.6 percentage points from a year ago.
“The average interest rate on new-vehicle loans is expected to rise 19 basis points to 6.81%, the highest October reading since 2023. This reverses the easing seen over the past several months, with rates up 28 basis points from August, adding to structural affordability pressures facing buyers.
“To manage monthly payments, consumers are using longer loan terms. A total of 13.3% of new-vehicle loans are forecasted to have terms of 84 months or longer, up 0.9 percentage points year over year, helping to partially bridge the affordability gap.
“Subprime penetration remains elevated from last year, with the mix trending to rise 1.5 percentage points from October 2025 to 11.0% this month, in part because many buyers with strong credit and the ability to accelerate their purchases did so last year.
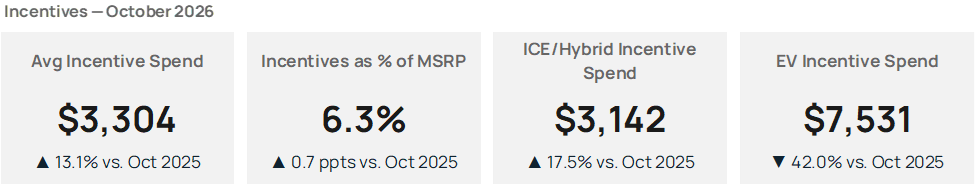
“To offset the affordability challenges, manufacturers are leaning harder into discounts to keep buyers in the market. Average incentive spending per vehicle is trending towards $3,304, a 13.1% increase from a year ago and the largest increase in the past four months. Incentives as a percentage of MSRP are expected to hit 6.3% in October, up 0.7 percentage points from October 2025.
“The divergence in manufacturer incentive strategies by powertrain continues to be evident in October. Incentive spending on traditional internal combustion engine and hybrid vehicles is expected to increase $468 per unit year over year, up 17.5% to $3,142 in October 2026. Meanwhile, EV incentives moved in the opposite direction, with a forecasted decline of $5,455 per unit or 42.0% to $7,531, from an elevated base last October.
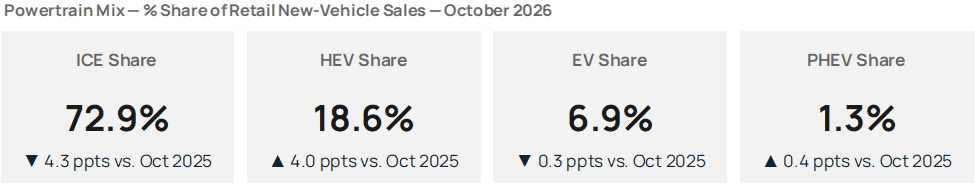
“Buyers continue to shift toward hybrids, with hybrid share of retail sales expected to reach 18.6%, up 4.0 percentage points from last year, due to elevated fuel prices and increased availability of hybrid vehicles. EV share is expected to be 6.9%, down 0.3 percentage points year over year.”
Global Sales Outlook
David Oakley, manager, Americas vehicle sales forecasts at GlobalData:
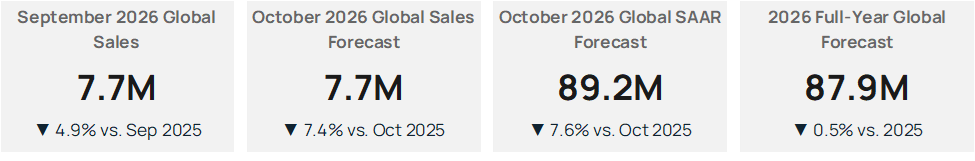
“September global light-vehicle sales are estimated to have declined 4.9% year over year to 7.7 million units. As has been the case for much of the year, sales declined sharply year over year in China, dragging down the global market despite some bright spots elsewhere. The global selling rate for September was estimated at 89.2 million units, down from 91.3 million units in August.
“The Chinese market saw a 25.6% year over year decrease in sales in September, excluding any vehicles intended for export. The market continues to struggle in the face of the removal of trade-in subsidies, even as Chinese exports surge. Though clearly not sufficient to fully offset China’s losses, India remains the most significant source of growth, with September sales estimated to have increased by 21.3% year over year. Compared with a year ago, tax reductions and relaxed financing conditions are providing the market with momentum during the festival season. Elsewhere, Western Europe and South America also expanded, but this was mitigated to some extent by lower sales in Eastern Europe and Korea.
“Global sales are expected to once again be dragged down by year-over-year declines in China, even while India continues to grow. October sales are expected to decline 7.4% from October 2025, to 7.7 million units. This would translate to a selling rate of 89.2 million units, down by 7.6% year over year. European sales may contract slightly as the Turkish market struggles with higher real interest rates, while the Middle East will be down sharply amid regional conflict.
“Our forecast for total global sales in 2026 now stands at 87.9 million units, compared to 88.3 million units a month ago. This forecast would represent a 4.8% year over year decrease, with the Chinese market expected to drag on sales until 2027.”
About JD Power
JD Power is a proven leader in business-critical data and intelligence to drive auto-related decisions with confidence and clarity. By leveraging unmatched proprietary data, advanced analytics and deep industry expertise, JD Power fuels original equipment manufacturers, retailers, lenders, insurers and partners to enhance their performance.
Since 1968, JD Power has delivered incisive guidance and intelligence about customer interactions with brands and products. To learn more about the company’s business offerings, visit JDPower.com.
Source: JD Power
